The Chronology of a Market Reversal
The current state of the condo market stands in stark contrast to the fervor of the pandemic-era housing boom. In September 2021, the market dynamics were inverted, with 25.1% fewer sellers than buyers, driven by historically low interest rates and a desperate scramble for living space. However, the intervening five years have triggered a dramatic correction. Since that peak, the number of active condo buyers has plummeted by 54%, while the inventory of sellers has surged by 36%.
This decline in buyer participation reached a critical inflection point in September, when the total count of condo buyers fell to an estimated 88,460—a 2.5% decrease from August and the lowest level observed in over a decade. Conversely, the supply side has remained persistent, with 197,248 active listings recorded in September, a 0.9% increase from the previous month. This structural imbalance has left sellers competing fiercely for an increasingly thin roster of qualified purchasers.
The Triple Threat: Insurance, HOA Fees, and Special Assessments
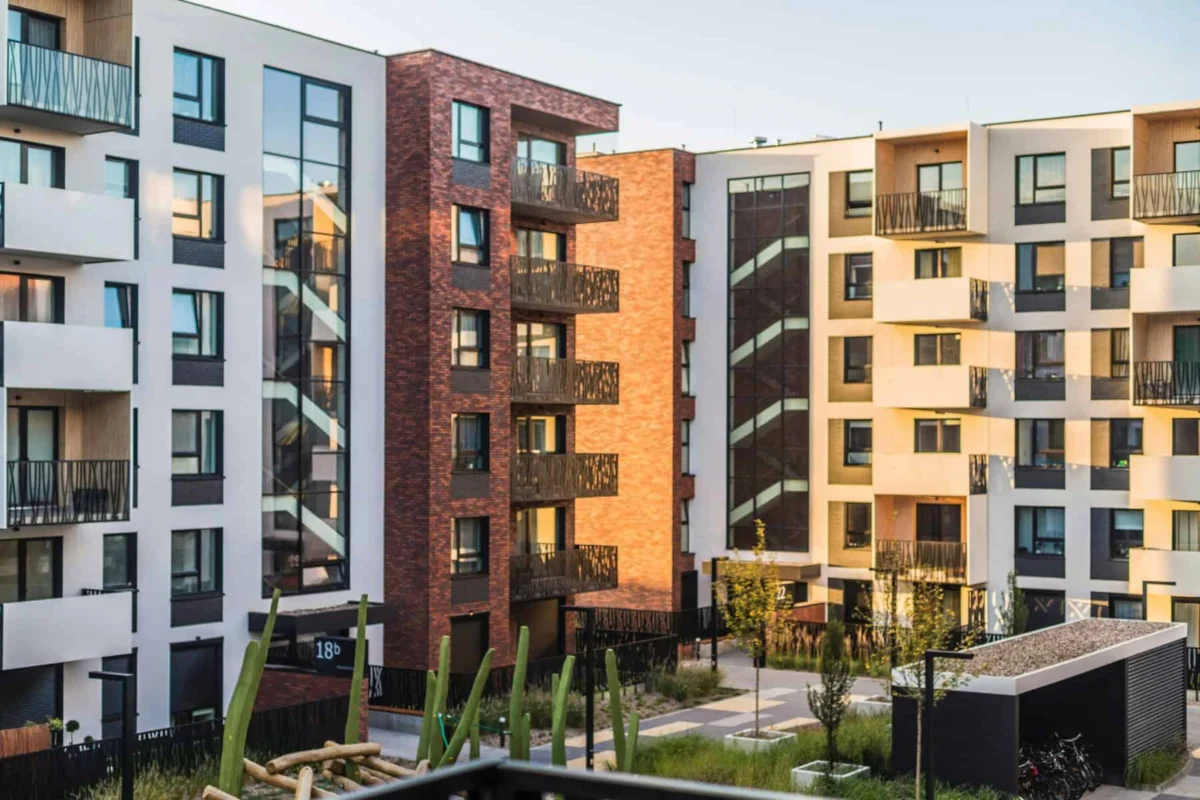
The cooling of the condo sector is not merely a reflection of broader economic trends, such as high mortgage rates; it is exacerbated by unique pressures that disproportionately affect vertical living. Unlike single-family homes, condominiums are subject to the financial health of the collective building or community, which is currently under significant duress.
In regions prone to environmental risks, such as Florida and Texas, the escalation of insurance premiums has reached a breaking point. These rising costs, coupled with mandatory contributions to Homeowners Association (HOA) funds and unexpected special assessments for necessary structural repairs, have significantly eroded the affordability of the condo market. For first-time homebuyers—who have historically viewed the condo market as an accessible entry point to homeownership—these costs are often prohibitive. Without the accrued equity of a prior home sale, many potential buyers are finding that the total monthly cost of ownership for a condo is increasingly difficult to justify, especially when compared to the relative stability of single-family housing.
Geographic Variations: From Texas to the New York Suburbs
The impact of this market shift is not distributed evenly across the United States. The Sun Belt, which saw an explosion of new construction during the last five years, is currently witnessing the most severe buyer-friendly conditions. Texas, in particular, dominates the list of markets where sellers outnumber buyers.
San Antonio reported the most extreme imbalance among the 50 most populous U.S. metro areas, with an estimated 459% more sellers than buyers. Houston and Austin followed, with 322% and 258% more sellers than buyers, respectively. Agents in these regions note that the influx of new construction, combined with the cooling of investor demand, has flooded the market with options. Furthermore, the local reliance on military-related relocation cycles, particularly in San Antonio, has contributed to a sharper-than-usual seasonal decline in demand once the peak transfer months pass.
In contrast, Nassau County, New York, stands as a notable outlier, functioning as the only metro area among those analyzed that remains a seller’s market. In this region, demand is sustained by a distinct demographic profile: buyers seeking the convenience of maintenance-free living, including those transitioning from urban centers to the suburbs, downsizers, and investors. Despite the prevalence of high common charges, the local appetite for the "lock-and-leave" lifestyle persists, keeping inventory tight relative to demand.
Economic Implications and the Price Correction
The systemic mismatch between supply and demand has finally begun to put downward pressure on pricing. In September, the national median condo sale price declined by 0.8% to approximately $339,000, marking the first year-over-year contraction in five months. Sellers, recognizing the shift in leverage, are increasingly forced to adjust their expectations. Data shows that roughly 37% of condos sold in September featured a price reduction, a stark increase from the 16% seen five years ago during the peak of the housing boom.
Furthermore, the "days on market" metric underscores the cooling velocity of the sector. The typical condo sold in September remained on the market for 63 days before going under contract, nearly doubling the 35-day duration observed during the competitive surge of the early 2020s.
Expert Perspectives and Strategic Advice
Real estate professionals advise that while the current market is technically "buyer-friendly," the definition of affordability has become more complex. Asad Khan, a senior economist at Redfin, emphasizes that the opportunity for buyers lies in the increased room for price negotiation. "For renters who have saved for a down payment and are ready to build equity, these buyer-friendly conditions are an opportunity," Khan notes. "Buyers have more options and a better chance of finding a place they like. Although condo prices and HOA fees remain relatively high, buyers have more room to negotiate price cuts, and condos are still generally more affordable than single-family homes."
However, the advice for those navigating this landscape is cautious. Cecilia Cordova, a Miami-based Redfin Premier agent, stresses the importance of deep due diligence regarding the financial health of the building. With rising instances of special assessments—charges levied on owners to cover major building repairs—potential buyers must look past the list price. "Researching the buildings you’d like to live in is the key to finding a financially healthy community and avoiding surprise assessment bills later," Cordova advises.
For those looking to sell in this challenging environment, the strategy has shifted from testing the market to aggressive pricing. "If you really need to sell, the strategy is to list it lower than anybody else in the same building," Cordova suggests. "It’s not time for you to try to experiment with a higher price."
The Broader Housing Context
The condo market’s current state is a microcosm of the wider housing sector, which is grappling with the lingering effects of high mortgage rates—hovering around 7.18% as of early November—and property prices that remain stubbornly close to historic highs. While the single-family home market is also seeing a surplus of sellers relative to buyers, the gap is significantly less extreme than that of the condo market.
The record-breaking surplus of condo inventory serves as a primary driver of the current buyer-friendly climate. Whether this trend persists depends on a variety of macroeconomic factors, including potential interest rate adjustments by the Federal Reserve and the continued ability of HOA boards to manage aging infrastructure without imposing unsustainable costs on residents. For now, the market remains a landscape of opportunity for the well-informed buyer, provided they can navigate the hidden costs of maintenance and the risks inherent in the current building-valuation cycle.
As the nation approaches the end of the year, the divergence between the condo sector and the broader residential market will remain a focal point for economists and prospective homeowners alike. The era of the "seller-take-all" market has effectively ended, replaced by a more selective, negotiation-heavy environment that rewards patience, liquidity, and meticulous research. For many, this reset represents the first genuine opportunity to enter the real estate market in years, provided they are prepared to weather the complexities of modern condominium ownership.