The calculus of urban real estate has shifted once again, presenting prospective homeowners in New York City with an increasingly protracted financial timeline. According to a comprehensive market analysis released by StreetEqual, the threshold at which purchasing a median-priced apartment becomes more economically advantageous than renting has stretched to nearly 15 years. This marks an increase of two full years compared to the calculations recorded in 2025, underscoring the compounding pressures of constrained housing inventory, high mortgage rates, and escalating rental costs across the five boroughs.
For decades, the "rent-or-buy" calculator has served as a staple tool for urban dwellers attempting to navigate the notoriously complex New York housing market. However, these models frequently rely on baseline assumptions that often fail to mirror reality: the immediate availability of a substantial down payment, eligibility for competitive mortgage rates, and a robust inventory of reasonably priced homes. In practice, acting strictly on financial optimization can lead buyers to trade a desirable rental in a vibrant neighborhood, such as Fort Greene, for a more modest, postwar co-op in an adjacent district. While the numbers might pencil out favorably on paper over a decade, the lifestyle compromises often complicate the decision.
The Anatomy of a Squeezed Market
Despite their inherent limitations, these analytical tools effectively capture broader economic pressures. The latest data reveals that a buyer purchasing a median-priced New York apartment—currently hovering around $900,000—must remain in the property for approximately 15 years to outpace the cumulative cost of renting the same unit. This extended timeline is primarily driven by an acute shortage of available housing stock, which simultaneously inflates both rental rates and purchase prices.
Market indicators from recent months illustrate the severity of this supply-demand imbalance. In October, 21 percent of all residential homes sold above their asking price, representing a notable increase from 18.9 percent during the same period the previous year. Furthermore, properties are moving at a brisk pace, spending a median of just 48 days on the market before entering contract.
Simultaneously, the rental sector is experiencing severe contractions. Rental inventory plummeted by 15.2 percent over the course of a single year, propelling asking rents upward. In Manhattan alone, the median asking rent surged by 8.6 percent. This upward trajectory builds upon an already historic peak; during the spring, median rents across New York City reached an unprecedented high of $4,120 per month.
Anomalies in the Luxury and Historic Districts
While the broader market trend pushes the break-even horizon further into the future, certain tony neighborhoods present striking exceptions to the rule. In select high-end enclaves, asking rents have climbed to such extraordinary heights that purchasing an apartment actually emerges as the more prudent financial strategy in a shorter timeframe.
Standard real estate wisdom generally dictates that buying only becomes financially sound if an owner intends to occupy the residence for at least ten years—allowing sufficient time for property appreciation to offset substantial closing costs, mansion taxes, and broker fees. Yet, pockets of the city are defying this rule.
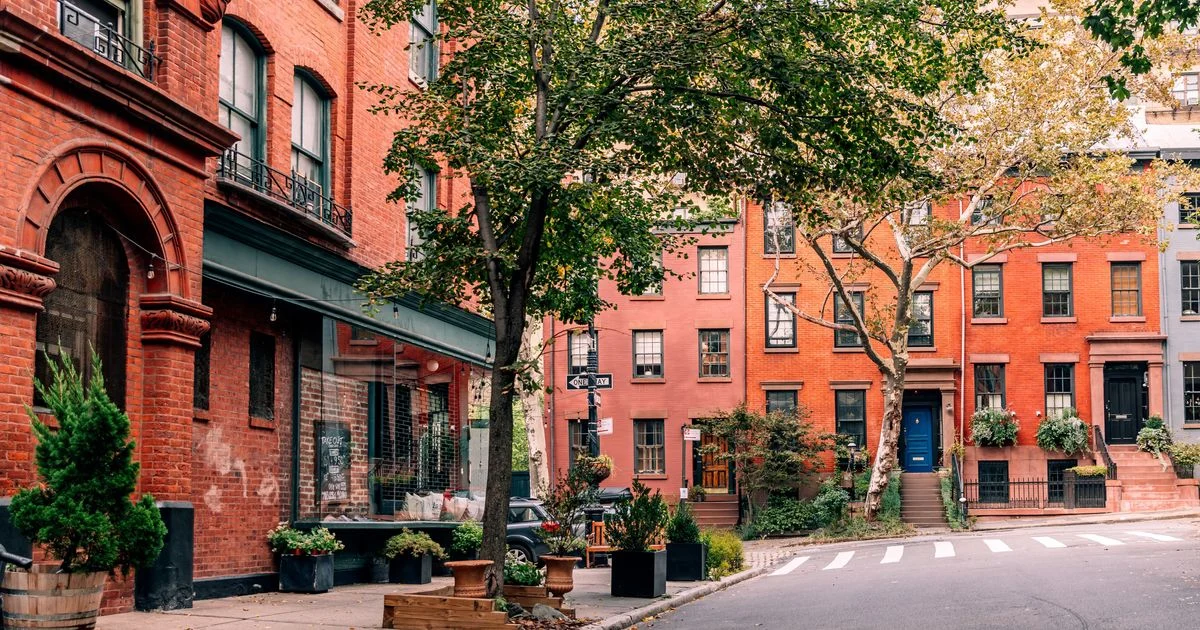
In Brooklyn Heights, for instance, the dynamics of a constrained rental pool have compressed the break-even timeline dramatically. With a median sales price of $870,000 in October and an annual median asking rent reaching $5,150 per month, a buyer would break even in just 6.8 years. Industry analysts note that while $5,150 typically secures only a one- or two-bedroom apartment in this historic neighborhood, the rapid convergence of costs is exacerbated by a dwindling rental inventory caused by the ongoing conversion of multi-family buildings into single-family townhouses.
A comparable scenario is unfolding in Gramercy Park. The neighborhood boasts a median sales price of $962,000, paired with a median rental cost of $5,500 per month. Consequently, buyers in Gramercy can expect to break even in approximately 7.2 years. While these figures confirm that the neighborhood remains exceptionally expensive, the rapid appreciation of rental costs makes acquisition more competitive with leasing than in standard market conditions.
Conversely, neighborhoods offering a faster break-even timeline through lower initial capital outlays remain concentrated in the outer boroughs. Areas such as Rego Park and Oakland Gardens in Queens, alongside Riverdale in the Bronx, present median sales prices around $400,000. Combined with relatively robust rental medians of $3,275 per month, the break-even horizon in these communities drops significantly to just 3.9 years.
The Cultural and Structural Uniqueness of New York Real Estate
New York City’s real estate ecosystem operates under economic laws distinct from nearly every other major metropolitan area in the United States. Approximately three-quarters of all New York City residents are renters, creating a massive, highly diverse tenant population that spans everything from unrenovated basement units to ultra-luxurious penthouses commanding tens of thousands of dollars per month.
In most American cities, renting is frequently viewed as a temporary stepping stone to homeownership or a lesser alternative for those unable to secure capital. In contrast, New York is one of the rare urban centers where a substantial segment of the population voluntarily chooses to sustain long-term tenancies, occasionally spending upwards of $30,000 a month on luxury rentals rather than entering the sales market.
Broader Economic Implications and Outlook
The widening break-even window carries significant implications for the city’s demographic stability and economic mobility. As the timeline required to recoup purchase costs extends to a decade and a half, first-time homebuyers face a higher threshold of long-term commitment in a volatile economic climate. This friction can discourage younger professionals and middle-class families from planting permanent roots, potentially accelerating outward migration to more affordable regional markets.
At the same time, the persistent tightness in both sales and rental inventories suggests that price moderation is unlikely in the near term. Unless municipal and state policymakers successfully implement large-scale housing production initiatives to alleviate the supply deficit, the delicate arithmetic of renting versus buying in New York City will remain heavily tilted in favor of landlords and sellers, leaving prospective buyers to weigh the heavy costs of patience against the steep price of admission.