As mortgage rates begin to retreat from their recent peaks, the national housing market is showing tentative signs of stabilization. According to the latest Housing Market Tracker from expert analyst Logan Mohtashami, the broader U.S. landscape is responding to improved affordability, even as supply constraints continue to dictate inventory levels. However, for real estate professionals, investors, and prospective homebuyers, relying solely on national headlines is a strategic error. The nuances of the current housing cycle are increasingly playing out at the municipal and even neighborhood level, where divergent trends can obscure the reality of local market health.
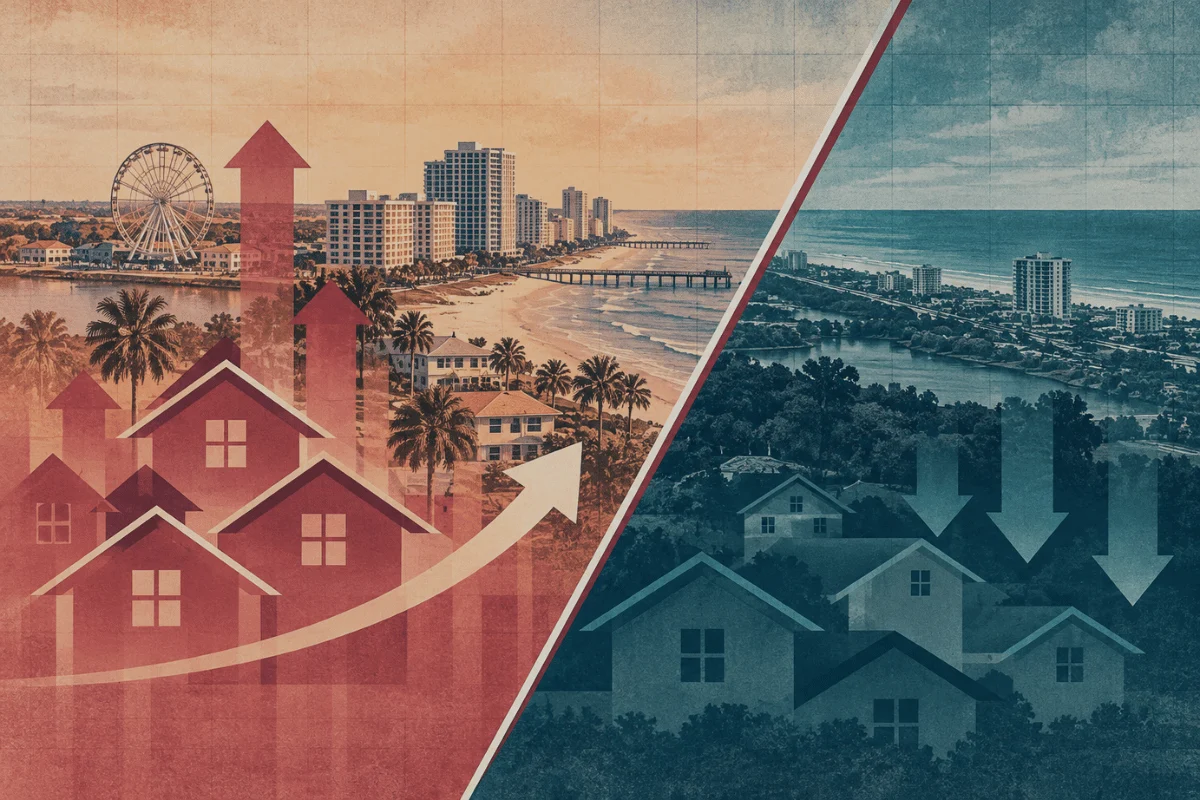
A striking case study of this phenomenon can be found in the Deltona-Daytona Beach-Ormond Beach metropolitan area of Florida. While the region recorded an aggregate increase in new pending listings of 20.2% year over year in October 2026, the underlying data reveals a fractured landscape. In some pockets of the metro, buyer demand is surging, while in others, momentum has stalled entirely. This disparity serves as a critical warning for industry stakeholders: national demand signals are often an average of wildly different local experiences.
The Anatomy of a Fragmented Market
The Deltona-Daytona Beach-Ormond Beach metro area provides a quintessential example of how internal market dynamics can contradict regional averages. While the 20.2% jump in pending listings suggests a robust recovery, the city-level breakdown tells a more complex story. In Ormond Beach, for instance, the market experienced a seismic shift, with new pending listings surging 116.7% year over year—climbing from 72 in October 2025 to 156 in October 2026. This aggressive growth suggests a localized influx of buyer interest that is not necessarily reflected elsewhere in the county.
Conversely, the city of Deltona, which serves as a namesake for the region, witnessed a 24.3% decline in new pending listings, dropping from 136 to 103 over the same timeframe. New Smyrna Beach followed a similar downward trajectory, recording a 25.3% decrease. These figures illustrate that even within a shared economic geography, consumer behavior is influenced by distinct local factors—ranging from school district performance and tax rates to localized employment growth and inventory variety.
For real estate agents and loan officers, these discrepancies are not merely statistical noise; they are operational realities. An agent operating in Ormond Beach is navigating a landscape of heightened competition and accelerated decision-making, while a professional in Deltona must adjust to a market characterized by buyer hesitation and fewer active opportunities. Ignoring these distinctions in favor of a monolithic regional or national outlook risks poor pricing strategy, inaccurate client expectations, and missed business opportunities.
Understanding Seasonal Anomalies
Seasonality is a cornerstone of housing market analysis, yet the timing and intensity of these cycles are rarely uniform. Traditionally, the autumn months mark a cooling period in residential real estate as the urgency of the summer selling season fades. However, the data from Volusia County demonstrates that historical seasonal norms are being challenged by current economic conditions.
In 2025, Ormond Beach saw a moderate increase in average weekly pending listings between September and October. By 2026, that seasonal lift was amplified significantly, suggesting that the local market’s reaction to interest rate fluctuations may be more elastic than in previous years. Meanwhile, Deltona exhibited a paradoxical trend: it experienced an increase in activity during the September-to-October transition in 2025, only to reverse that pattern in 2026 with a notable decline.
This volatility underscores the danger of applying “rule of thumb” seasonality to local markets. Professionals must look beyond the calendar to understand the "why" behind these shifts. Is a decline in pending listings a sign of a market correction, or is it simply a return to historical seasonal norms after a period of over-performance? By dissecting these patterns, analysts can distinguish between fleeting fluctuations and fundamental shifts in market trajectory.
The Four Pillars of Local Market Intelligence
To navigate this environment, industry professionals should focus on four core metrics that, when viewed in tandem, provide a comprehensive picture of market health.
1. New Pending Listings: Gauging Momentum
This metric serves as the primary indicator of current buyer demand. By comparing year-over-year performance over consecutive weeks, stakeholders can identify if a market is gaining or losing heat. A sustained deviation from typical seasonal patterns—such as a smaller-than-usual decline in the winter months—can be an early warning sign of a shift in local affordability or buyer sentiment.
2. New Listings: Assessing Supply Dynamics
Understanding the influx of new inventory is vital to determining the "competition gap." When new pending listings outpace the volume of new listings, buyers are effectively absorbing supply, which can lead to upward pressure on prices. Conversely, if new inventory is flooding the market faster than buyers can clear it, sellers may find themselves in a weaker negotiating position.
3. Price Reductions: Measuring Seller Alignment
The frequency of price reductions is a direct reflection of whether seller expectations are meeting buyer realities. A rising share of listings with price adjustments indicates that initial list prices may be misaligned with current demand, forcing sellers to pivot. For a loan officer, this is a key data point when helping clients understand the negotiation landscape.
4. Days on Market: The Velocity of Transactions
Median days on market acts as a barometer for urgency. Shorter durations combined with high pending volume confirm a high-demand environment. Longer durations, however, suggest a "wait-and-see" approach from buyers. When this metric increases, it is often a lagging indicator that the market is beginning to favor the buyer.
Synthesizing the Data for Strategic Advantage
No single metric offers a complete view. The true power of market intelligence lies in the synthesis of these signals. For instance, a rise in pending listings might seem like a positive signal of growth. However, if that rise is accompanied by an increasing number of price reductions and a stagnation in the time properties spend on the market, it suggests that the market is struggling to clear inventory despite increased activity. This is the "Port Orange Effect," where the lack of price cuts might look like a positive, but the lack of sustained pending growth suggests a market that is simply flat rather than booming.
Industry experts emphasize that the objective of this data-driven approach is not to act as a crystal ball. Predicting the exact moment of a market shift is notoriously difficult. Instead, the goal is to cultivate a deep, evidence-based understanding of the "now." When professionals can explain why a local market is moving in a specific direction—using data to support their insights—they transform from simple transaction facilitators into trusted strategic advisors.
Broader Implications for the Industry
The current market environment, characterized by shifting mortgage rates and localized inventory constraints, has profound implications for the professional services sector. For brokerages, the focus is shifting toward hyper-local specialization. Teams that can provide granular data on specific ZIP codes are finding greater success in winning listings and securing buyer loyalty than those relying on generalized regional reports.
For lending institutions, the implications are equally significant. Underwriting and risk assessment departments are increasingly looking at micro-market data to determine loan performance potential. When a market shows signs of softening through rising days on market or increased price reductions, lending teams can adjust their outreach and risk appetite accordingly.
Furthermore, the Florida data serves as a cautionary tale for those who rely on headlines. The national narrative that "housing is stabilizing" is technically accurate, but it is a top-down view that hides the bottom-up reality. In the current economic cycle, where affordability is the primary hurdle for most households, the specific economic drivers of a community—local tax levies, job market stability, and regional inventory levels—are the real determinants of success.
Moving Forward: The Data-Driven Standard
As we look toward the remainder of the decade, the reliance on real-time, actionable data will only increase. The tools provided by platforms like HousingWire Intelligence allow for this level of precision, enabling professionals to customize their view of the market down to the community level.
The takeaway for any professional involved in the residential housing market is clear: the national trend is merely the context, not the conclusion. The real story of the housing market is written at the local level. By tracking the four pillars of buyer activity—new pending listings, new inventory, price adjustments, and market velocity—professionals can build a more resilient business strategy. In an era of uncertainty, the ability to interpret local data is not just an advantage; it is the fundamental requirement for navigating the modern real estate landscape.
The distinction between a thriving local market and one that is struggling is often found in the data that others overlook. As the Florida experience demonstrates, success in the current climate requires a shift in mindset: moving away from general assumptions and toward a rigorous, localized analysis of the factors that truly move the needle for buyers and sellers. Those who master this shift will be the ones best positioned to thrive in the coming years.