The high-stakes world of mortgage lending recruitment has once again come under legal scrutiny as Movement Mortgage, one of the nation’s prominent lenders, pursues a significant financial recovery from two former loan officers. In a recent move to solidify its position, the company has petitioned the U.S. District Court for the Western District of North Carolina to transform an arbitration award into a formal court judgment. The dispute centers on $1.235 million in "start-up payments" provided to Victor Shkolnikov and Igor Velyunskiy, who departed the firm well before the completion of their contractual obligations. This case highlights the increasingly common, yet contentious, practice of using hefty signing bonuses—often structured as forgivable loans—to attract top-tier talent in a hyper-competitive housing market.
The Anatomy of the Dispute
The conflict originated in March 2022, when Movement Mortgage onboarded Shkolnikov and Velyunskiy. As part of their employment agreements, the lender issued substantial capital to the two loan officers. Shkolnikov was granted $835,000, while Velyunskiy received $400,000. These payments were not framed as simple signing bonuses but rather as advances on future compensation, tethered to a 36-month service commitment.
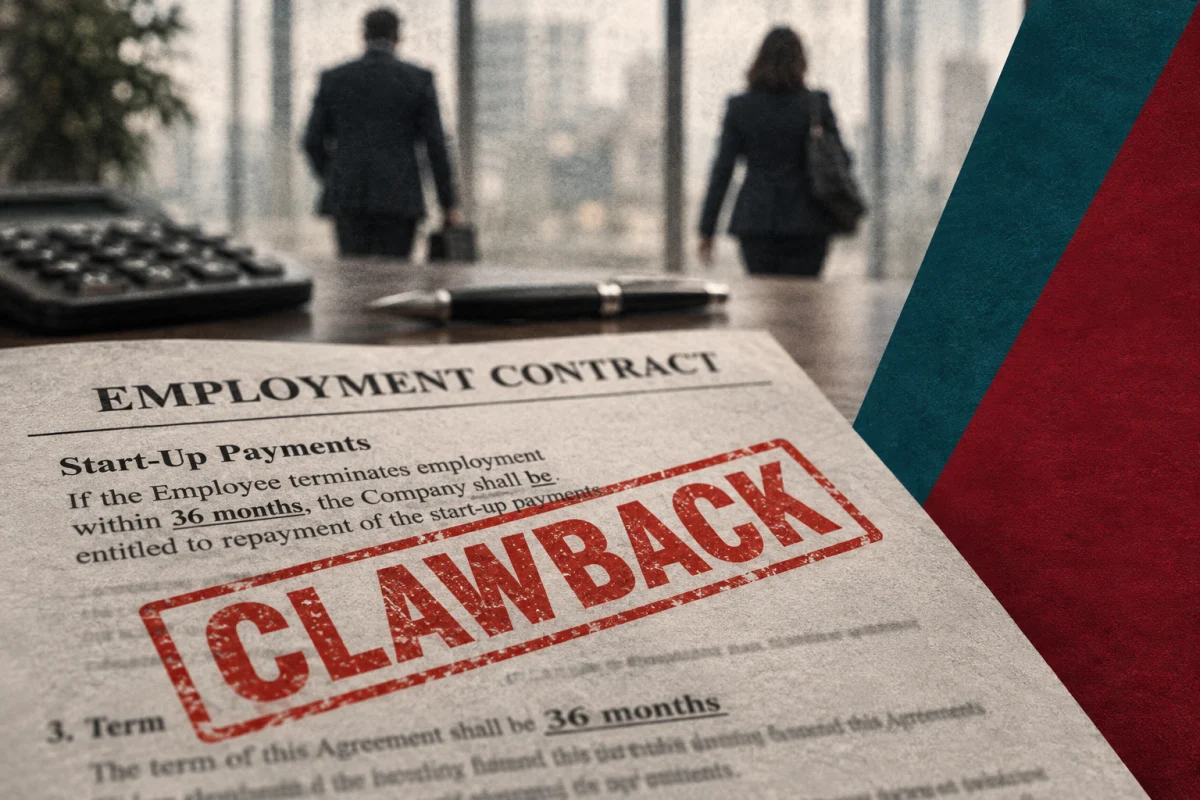
According to the terms established in their respective employment contracts, the officers were required to maintain their employment with Movement for three consecutive years. If an officer resigned or was terminated prior to the conclusion of this 36-month window, the entirety of the start-up payment was deemed immediately due and payable to the company within 30 days.
By March 2023, roughly 12 months into their tenure, both officers exited the company. Shkolnikov transitioned to a role as a loan originator with United Lending Team in Illinois, while Velyunskiy joined Smart Rate Lending LLC. Following their departures, Movement Mortgage initiated arbitration proceedings in February 2024 to recoup the funds, arguing that the breach of contract was clear and the repayment terms were unambiguous.
Chronology of the Legal Proceedings
The legal battle unfolded over several months, marked by aggressive counterclaims from the defendants. The timeline of the dispute is as follows:
- March 2022: Victor Shkolnikov and Igor Velyunskiy join Movement Mortgage, receiving a combined $1.235 million in start-up advances.
- March 2023: Both loan officers leave the company, failing to fulfill the 36-month service requirement.
- February 2024: Movement Mortgage initiates formal arbitration to recover the funds.
- Mid-2024: The defendants file counterclaims alleging breach of contract, unjust enrichment, fraudulent inducement, and violations of the Truth in Lending Act (TILA).
- July 2024: Arbitrator H. William Constangy rules in favor of Movement Mortgage, confirming the validity of the employment contracts and dismissing all counterclaims.
- November 2024: Movement Mortgage files a motion in the U.S. District Court for the Western District of North Carolina to confirm the arbitration award as a legal judgment.
Analysis of the Arbitrator’s Ruling
The ruling delivered by Arbitrator H. William Constangy in July serves as a significant validation of the "clawback" model prevalent in the mortgage industry. By dismissing the counterclaims of fraudulent inducement and TILA violations, the arbitrator effectively affirmed that sophisticated employees—such as high-producing loan officers—are bound by the clear language of their employment agreements.
Crucially, the ruling imposed an interest penalty on the outstanding debt. The repayment amount is subject to an 8% annual interest rate, calculated from April 2023, which the arbitrator identified as the date of the breach. While the arbitrator declined to award legal fees to either party—forcing both sides to absorb their own significant litigation costs—the financial burden on Shkolnikov and Velyunskiy remains substantial once the accrued interest is calculated.
The Role of Signing Bonuses in Mortgage Recruitment
The mortgage industry is notoriously cyclical and highly competitive, particularly regarding the recruitment of "producers"—loan officers who bring established referral networks and a consistent pipeline of business. To lure these individuals away from competitors, lenders often offer "sign-on bonuses" that are essentially structured as promissory notes.
These notes typically include a "forgiveness schedule," where a portion of the bonus is written off for every month or year the employee remains with the company. The goal is to incentivize long-term retention and protect the lender’s investment in the recruiting process. However, as the industry faces market volatility and shifting interest rate environments, the pressure to maintain volume often leads to higher turnover rates, which in turn leads to a spike in litigation surrounding these clawback provisions.
Broader Industry Implications
The case involving Movement Mortgage is not an isolated incident but rather a symptom of a larger trend in the financial services sector. As companies look to protect their bottom lines, they are increasingly willing to pursue former employees in court to recover upfront capital. This strategy serves two purposes: it allows the firm to recoup actual financial losses, and it sends a deterrent signal to other employees who might be considering a move to a competitor.
However, the legal landscape for these clawbacks is complex. While arbitration agreements often favor the employer, courts have occasionally scrutinized these contracts to ensure they do not violate labor laws or state-specific employment regulations. The fact that the loan officers in this instance attempted to invoke the Truth in Lending Act suggests a defensive strategy aimed at framing these bonuses not as salary advances, but as predatory lending instruments. The arbitrator’s decision to reject this characterization underscores the difficulty of challenging standard corporate employment contracts once they have been signed.
Official Responses and Future Outlook
As of the latest reports, neither Movement Mortgage nor the legal representatives for Shkolnikov and Velyunskiy have provided detailed statements regarding the ongoing court petition. The silence from both camps is standard in such disputes, as the primary objective now shifts from the arbitration chamber to the enforcement of the judgment.
For Movement Mortgage, the goal of the November filing in the Western District of North Carolina is clear: to obtain a federal judgment that can be enforced through mechanisms like wage garnishment, asset liens, or bank account levies. Should the court grant the motion, the lender will possess a powerful set of legal tools to secure the $1.2 million, plus the accrued interest.
For the wider industry, this case serves as a cautionary tale. Loan officers and other high-level professionals are being reminded that signing bonuses often come with significant strings attached. The legal enforcement of these contracts is becoming more robust, and the financial consequences of leaving an employer before the end of a contractual term can be severe. As lenders continue to navigate a cooling housing market, the reliance on these clawback provisions is unlikely to diminish, and further litigation of this nature is expected to remain a fixture of the mortgage business landscape.
Final Considerations
The outcome of this case will likely bolster the confidence of mortgage lenders who utilize similar recruitment strategies. By successfully navigating the arbitration process and moving to secure a court judgment, Movement Mortgage has demonstrated the efficacy of its contractual protections. Conversely, the case highlights the risks for loan officers who may feel pressured by market conditions or better offers from competitors to abandon their commitments. As the industry moves forward, the intersection of talent acquisition and rigid contractual enforcement will remain a critical area of legal and professional focus, influencing how lenders structure their recruitment deals and how employees evaluate the long-term viability of their employment agreements.