The United States labor market has once again demonstrated a remarkable degree of resilience, defying conventional economic expectations in the face of a week characterized by significant geopolitical shifts and fluctuating capital markets. Despite a robust jobs report released this Friday, mortgage rates remained surprisingly stagnant, signaling a potential decoupling of traditional labor data trends and long-term borrowing costs. This latest data release underscores a broader trend observed throughout 2026: a labor market that continues to outpace the performance seen in 2025, maintaining its long-standing reputation as an economic outlier capable of absorbing immense external pressure.
The U.S. Bureau of Labor Statistics (BLS) reported that nonfarm payroll employment increased by 165,000 in October. While market analysts frequently anticipate that such "blowout" figures will trigger a surge in bond yields and mortgage rates—particularly given the Federal Reserve’s hawkish monetary policy stance—this week’s reaction was decidedly muted. The unemployment rate remains steady at 4.1%, a notable improvement from the 4.5% levels recorded during the previous calendar year. This stability provides the Federal Reserve with a clearer mandate to prioritize inflation management, as the labor sector has demonstrated that it does not currently require extraordinary intervention to prevent systemic decline.
A Chronology of Resilience: From 2011 to 2026
To understand the current strength of the labor market, one must view it through the lens of the "honey badger" phenomenon—a term coined to describe an economy that remains unfazed by external shocks. Since 2011, with the singular exception of the brief but severe disruption caused by the COVID-19 pandemic, U.S. labor data has consistently defied forecasts of recession.
In 2023, the U.S. reached a post-pandemic unemployment low of approximately 3.4%. While the current 4.1% rate represents a marginal increase from that historical trough, economists argue that the context has shifted. Labor force growth has decelerated, and the "break-even" number—the volume of monthly job creation required to maintain a stable unemployment rate—has dropped significantly. While some aggressive projections suggest a break-even point near zero, most institutional analysts, including those aligned with Federal Reserve modeling, estimate the threshold to be between 33,000 and 78,000 jobs per month. By consistently exceeding these benchmarks, the economy has maintained a structural buffer that prevents the rapid unemployment spikes typically associated with early-stage recessions.
Sector-Specific Performance and the AI Influence
The October jobs report revealed a nuanced picture of industrial health. Professional and business services led the growth, posting one of the most significant monthly gains in recent years. This surge is complemented by continued expansion in the healthcare and transportation and warehousing sectors. Conversely, the manufacturing sector showed modest gains, while construction employment experienced a slight softening.
The construction sector remains a critical bellwether for the broader economy. Historically, a downtrend in residential construction employment is a primary indicator of an approaching recession. However, the current cycle has been marked by a departure from historical norms. Builders have aggressively utilized rate buydowns to incentivize demand, effectively keeping new home sales consistent with 2019 levels despite elevated interest rates. Furthermore, the robust nature of the remodeling market has provided a secondary floor for construction labor, preventing the sector from entering the expected downturn.
A looming question for the sector involves the intersection of artificial intelligence and infrastructure. As the AI boom fuels the construction of massive data centers, the industry has seen a unique boost in activity. Should there be a cooling in the AI sector—either through market saturation or increased regulatory scrutiny—the impact on construction labor would likely be immediate. Analysts are currently monitoring whether a slowdown in capital expenditure from major tech firms could lead to a contraction in commercial construction employment, potentially serving as the first sign of a broader economic cooling.
The Dynamics of Yields and Mortgage Rates
The week’s volatility was driven less by the jobs report and more by the unpredictable nature of the equities market, particularly concerning the technology sector. The correlation between AI-related stock volatility and the 10-year Treasury yield was evident throughout the week. For instance, as stock prices for major infrastructure players like CoreWeave fluctuated by as much as 10% in pre-market trading, bond yields responded in kind, only to retract as the broader market sought equilibrium.
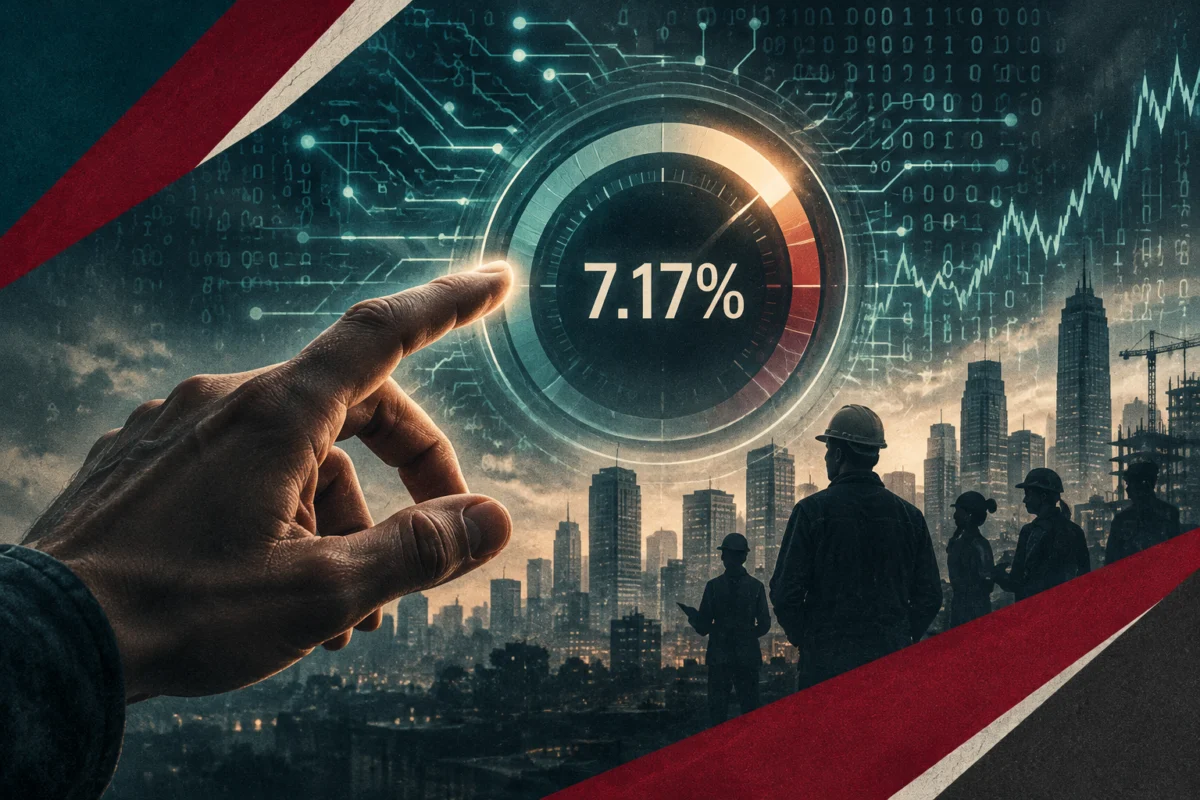
By the close of the week, the 10-year Treasury yield sat at 4.86%, and mortgage rates remained flat at 7.17%. This stability, despite strong macroeconomic data, suggests that market participants have already priced in much of the Fed’s hawkish outlook. The market’s refusal to react aggressively to the jobs data indicates a "weekend fatigue," where traders have largely moved past the immediate noise of monthly payroll releases to focus on broader, structural factors such as trade policy and geopolitical developments.
Implications of the New Legislative Landscape
The political climate has played an outsized role in investor sentiment this week. With shifting expectations regarding trade policy and international conflicts—specifically involving Iran—market participants are recalibrating their risk assessments. The hope for a de-escalation in trade tensions, coupled with the potential for Congress to introduce policies that could optimize economic performance, has created a unique environment for the bond market.
Industry experts, including those from HousingWire, have suggested that there are specific policy levers the new Congress could pull to mitigate the impact of high interest rates. These discussions are moving beyond simple monetary policy to include structural reforms that might encourage housing supply and stabilize the cost of borrowing. As the AI boom faces increased Congressional interest regarding its long-term viability and regulatory requirements, the market is beginning to factor in a potential "soft landing" scenario where the technology sector continues to grow, albeit at a more sustainable, regulated pace.
Analysis: Why the Market Isn’t Panicking
The lack of a sharp reaction to the strong jobs report can be attributed to three primary factors:
- Labor Market Decoupling: The labor market’s strength is no longer viewed solely as an inflationary catalyst. With the unemployment rate stabilized at 4.1%, the market views this as a sign of sustainable growth rather than an overheating economy.
- Productivity and Efficiency: The integration of AI and automated business services has allowed for growth in output without the same inflationary wage-price spirals seen in previous decades.
- Market Fatigue: After a week of intense geopolitical news and technology sector volatility, the bond market has shown signs of consolidation. Yields are currently hovering in a range that investors find acceptable, reducing the likelihood of a knee-jerk reaction to standard economic reports.
Looking Ahead: The Final Quarter of 2026
As the economy moves into the final stages of the year, the focus will remain on whether the labor market can continue to defy expectations. The critical indicators to watch will be the sustainability of the residential construction sector, the cooling or acceleration of AI-related infrastructure projects, and the Federal Reserve’s interpretation of the latest inflation data in the context of a healthy job market.
While the "honey badger" labor market has remained resilient, the structural challenges of high mortgage rates and the potential for a regulatory-induced slowdown in tech remain significant headwinds. However, as the data from the past week has shown, the U.S. economy currently possesses a surprising ability to absorb volatility without compromising its foundational strength. For prospective homebuyers and market participants, the stabilization of rates at the end of this tumultuous week offers a brief, if cautious, window of predictability in an otherwise unpredictable economic cycle.