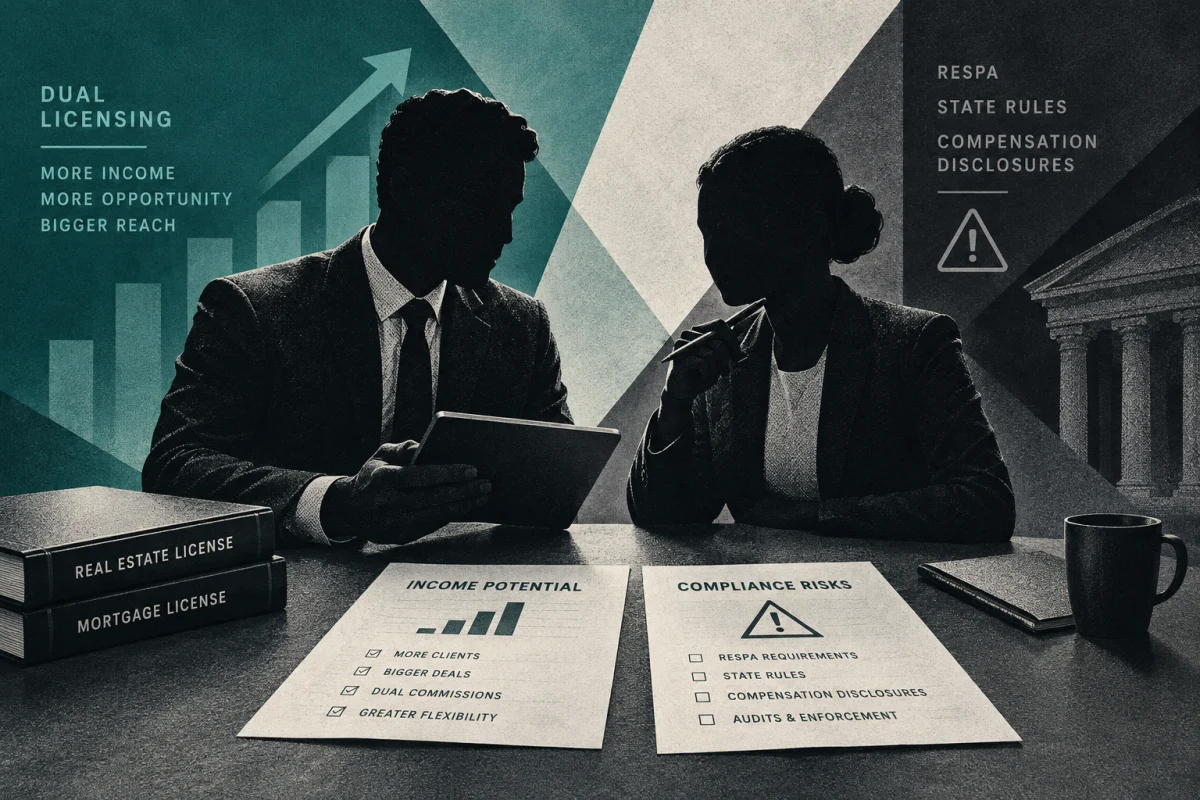
As the domestic housing market grapples with the dual pressures of elevated mortgage interest rates and restricted inventory, real estate professionals are increasingly looking toward diversification to sustain their bottom lines. Among the most prominent emerging trends is the pursuit of dual licensing, a practice that allows a single professional to function as both a licensed real estate agent and a mortgage loan officer (MLO). By consolidating these two pivotal roles, practitioners are attempting to gain greater control over the transaction lifecycle, capture additional revenue streams, and provide a more seamless experience for clients.
A comprehensive analysis recently conducted by RETR, a real estate data analytics firm, has shed light on the prevalence of this practice. The study identified 3,729 instances where a real estate agent’s top-producing loan officer shared the exact name as the agent, suggesting a high probability of dual licensure or significant professional overlap. The data highlights a strong geographic concentration of this trend: California alone accounted for 40% of these matches, while a combination of California, Florida, Texas, and Arizona represented nearly 71% of the total identified dual-licensed population.
The Evolution of the Dual-License Model
The shift toward dual licensing is not necessarily a new phenomenon, but it has gained significant momentum in the current economic cycle. In the years following the 2008 financial crisis, the regulatory environment tightened considerably, leading to a period where the industry focused heavily on specialization. Mortgage origination and real estate brokerage were largely treated as distinct silos, governed by different sets of federal and state laws.
However, the post-pandemic housing market—characterized by a cooling in transaction volume and increased competition among agents—has forced a re-evaluation of this separation. As commissions face downward pressure and the volume of home sales decreases, agents are seeking ways to capture a larger share of the total transaction value. For many, the MLO license serves as a logical extension of their existing skill set, allowing them to advise clients on financing, interest rates, and loan programs long before the search for a property even begins.
While the RETR study provides a significant baseline for understanding the scope of this trend, it is essential to note that the methodology relies on name-matching, which serves as a proxy rather than an absolute audit of dual licensure. The data does not account for professionals who may hold both licenses but keep their operations strictly separated, or those who utilize the MLO credential primarily for educational purposes rather than active origination.
A Practitioner’s Perspective on Market Control
For industry participants, the decision to obtain an MLO license is frequently driven by a desire for client advocacy. Shawn McNeil, broker and owner of HomeFlo and an active loan officer with Mpire Financial Group, exemplifies this transition. After nine years as a real estate agent, McNeil secured his MLO license approximately 18 months ago. His motivation was rooted in a recurring frustration: witnessing his high-net-worth clients and personal friends secure unfavorable financing through large-scale retail lenders.
“I would watch my big, high-dollar, personal friends go to these big-box retailers and just get absolutely crushed with an interest rate,” McNeil noted in an interview. “I was like, at first, I’m going to go get licensed so that I can talk through these things and be knowledgeable in this.”
McNeil now splits his professional time roughly 50/50 between real estate brokerage and mortgage origination. His client base consists primarily of investors and personal acquaintances who value the consolidated expertise. While he emphasizes that he does not act as both the agent and the lender on every transaction—preferring to refer clients to other lenders when a loan product falls outside his specific expertise—he believes the dual-license model is poised for growth.
McNeil attributes this anticipated expansion to the democratization of information. As artificial intelligence and digital platforms make it easier for professionals to research complex mortgage guidelines and underwriting requirements, the technical barrier to entry for the mortgage side of the business is effectively lowering.
Compliance and the Regulatory Tightrope
Despite the potential for increased revenue and improved service, the dual-licensing model is fraught with complex regulatory hurdles. The Real Estate Settlement Procedures Act (RESPA) stands as the most significant guardrail in this space. RESPA prohibits the payment of kickbacks or referral fees for the referral of settlement services, a rule that remains strictly enforced by the Consumer Financial Protection Bureau (CFPB).
Professionals operating under both licenses must ensure that their business practices do not create a conflict of interest or a violation of anti-steering provisions. This requires a robust internal compliance framework. McNeil, for example, has worked extensively with legal counsel to draft comprehensive disclosure documents. These disclosures are provided to every brokerage client, informing them that he is a licensed loan officer and the owner of the brokerage, regardless of whether they ultimately choose to utilize his mortgage services.
“We require 100% disclosure,” McNeil said. “Even if you’re not using my services, we still disclose to you that I am a licensed loan officer and I own the real estate brokerage.” These disclosures are provided electronically before a transaction reaches the contract stage, ensuring that clients are fully informed of the professional’s dual role.
Failure to maintain these standards can lead to severe penalties, including the loss of both licenses, heavy fines, and potential litigation. As the trend grows, regulators are expected to keep a closer eye on dual-licensed professionals to ensure that the convenience of a one-stop-shop model does not come at the expense of consumer protection.
Broader Market Implications
The rise of the dual-licensed professional carries several implications for the broader real estate ecosystem. First, it suggests a trend toward industry consolidation. If agents can successfully capture the mortgage component of a deal, the traditional referral pipeline—where agents send leads to external loan officers—may begin to shift. This could put pressure on independent mortgage brokerages and large-scale retail lenders who rely heavily on agent referrals to fill their pipelines.
Second, the availability of AI-driven tools is accelerating this shift. Technology that once required a team of analysts can now be accessed by individual agents, allowing them to navigate the nuances of government-backed loans, jumbo mortgages, and investment property guidelines with greater speed and accuracy.
Finally, the trend reflects a broader consumer preference for convenience. In an era where consumers are accustomed to integrated digital experiences, the ability to work with a single, trusted advisor who understands both the property and the financing can be a powerful value proposition.
However, critics of the model argue that it may limit a client’s options. If an agent-lender is incentivized to steer a client toward their own mortgage products, the client may lose the benefit of a competitive, market-wide search for the best interest rates. The success of the dual-licensing model, therefore, rests entirely on the transparency and ethical conduct of the practitioner.
Looking Ahead
While the RETR analysis does not definitively track the profitability or the long-term sustainability of the dual-license model, the anecdotal evidence from practitioners suggests that it is a viable strategy for those willing to master the complexities of both industries. As the housing market continues to evolve, the distinction between "selling a home" and "financing a home" may become increasingly blurred.
Whether this trend represents a permanent structural change or a cyclical response to current market conditions remains to be seen. As interest rates eventually stabilize and market volume potentially rebounds, the demand for this dual-competency will serve as a key metric for industry observers. For now, agents looking to differentiate themselves in a crowded, high-stakes market are likely to continue viewing the MLO license not just as a badge of expertise, but as a critical component of their business strategy for the years ahead. As more professionals enter this space, the industry will need to strike a delicate balance between driving innovation in the transaction process and maintaining the rigorous regulatory compliance that keeps the housing market stable for consumers.