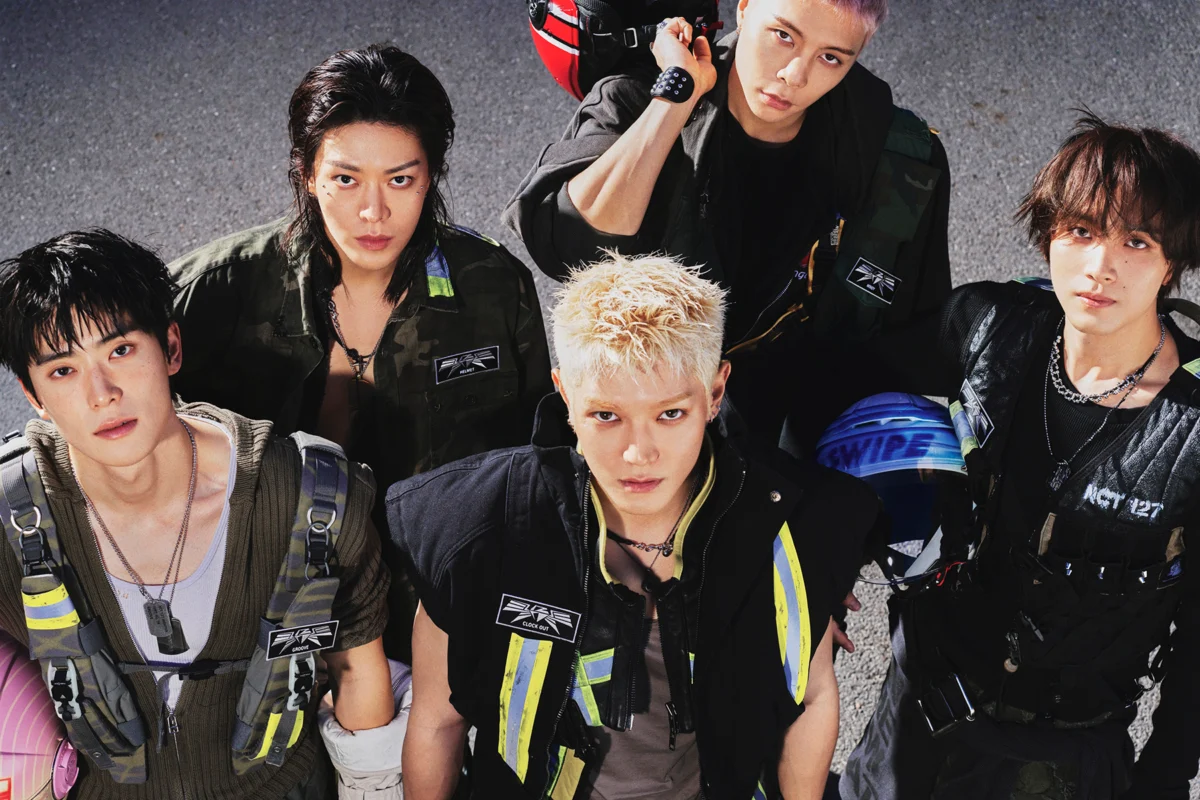
SM Entertainment, one of South Korea’s pioneering K-pop powerhouses and the architect behind global sensations like NCT and aespa, faced a challenging financial quarter, leading to a significant contraction in its market valuation. On Wednesday, Nov. 4, the company’s share price declined by more than 7% in morning trading following the release of a quarterly report that revealed an unexpected net loss. This fiscal downturn represents a stark departure from the robust performance seen during the same period in the previous year, highlighting the complex financial trade-offs inherent in the transition from a domestic-focused release cycle to a global-first growth strategy.
The company reported revenue of 291.1 billion Korean won ($205.2 million) for the quarter. While this figure reflects the continued scale of SM’s operations, it represents a 9% year-over-year decline in total revenue. More concerning to shareholders and market analysts was the operating profit of 35.5 billion Korean won ($25 million), a 26% drop from the same quarter in the previous fiscal year. Most notably, the company swung from a net profit of 44.7 billion Korean won ($31.5 million) a year ago to a net loss of 1.1 billion Korean won ($775,000) for the current period.
The Strategy Behind the Dip: Prioritizing Global Reach
During a conference call with investors and industry analysts, SM Entertainment’s Chief Investment Officer, Jeongmin Jang, provided a comprehensive breakdown of the factors influencing the bottom line. Central to the explanation was a deliberate strategic pivot: the intentional reduction of major domestic album releases to facilitate the long-term international expansion of the label’s roster.
"New album sales volume decreased by approximately 70% year over year as our major artists focused on expanding their overseas activities," Jang explained. This shift is part of a broader industry trend where K-pop agencies are increasingly looking to establish deep-rooted footprints in North American, European, and Southeast Asian markets. By prioritizing touring, international award show appearances, and localized brand partnerships, SM is attempting to diversify its revenue streams beyond the traditional physical album sales model that has long anchored the K-pop business.
The raw data confirms this shift in activity. Sales of physical and digital music—once the primary engine of growth for SM—fell by 51% to 47.1 billion KRW ($33.21 million). The company moved 1.67 million units during the quarter, a figure heavily bolstered by the performance of NCT 127’s latest album, BLINGY. While the release was a commercial success, it was insufficient to offset the year-over-year volume drop resulting from the company’s leaner release calendar.
Currency Volatility and Macroeconomic Headwinds
Beyond the strategic shift in release frequency, SM Entertainment pointed to external macroeconomic pressures that eroded profit margins. The strengthening of the Korean won played a significant role in the company’s bottom-line performance.
"The net loss is primarily due to foreign exchange-related losses resulting from the appreciation of the Korean won," Jang stated during the earnings call. For a company that generates substantial revenue in foreign currencies—particularly U.S. dollars and Japanese yen—through global tours and licensing, the volatility of exchange rates can create significant accounting discrepancies. When the local currency appreciates against the dollar, the repatriated value of overseas earnings decreases, which can turn a profitable operating performance into a net loss when converted back into the company’s reporting currency.
Identifying Growth Pillars: Licensing and Brand Partnerships
Despite the decline in physical music sales, the quarterly report highlighted several areas of robust growth that suggest the company’s diversification strategy is beginning to take root. Revenue from Intellectual Property (IP) licensing and merchandise—referred to by the company as MD/licensing revenue—climbed by 23.5% year over year, reaching 62.1 billion Korean won ($43.78 million).
This growth indicates that SM is successfully leveraging the strength of its artists’ brands in non-musical sectors. By deepening collaborations in fashion, cosmetics, and lifestyle goods, the agency is capturing value from the broader "fan economy" rather than relying solely on the lifecycle of a single music release.
Furthermore, revenue from artist appearances grew by 21.3% to 29.2 billion Korean won ($20.6 million). This segment encompasses performance fees at international music festivals, appearances at major global award ceremonies, and high-value advertising contracts. These results suggest that while the "album-first" model is undergoing a contraction, the "brand-first" model—which views K-pop stars as global lifestyle influencers—is gaining traction.
Chronology of the Quarter’s Performance
The events of this quarter reflect a broader timeline of transition for SM Entertainment:
- Early Q3: The company initiated a reduced release schedule to accommodate the intensive tour rehearsals and international travel requirements for artists such as NCT 127 and aespa.
- Mid-Quarter: Sustained global promotional activities resulted in a surge of advertising and licensing contracts, offsetting some of the decline in domestic music sales.
- Quarter-End: The combination of lower physical volume and currency fluctuation led to the reported net loss, surprising some analysts who had anticipated a smaller buffer.
- November 4: Formal announcement of the quarterly earnings triggers a 7% decline in share value as the market reacts to the net loss.
Industry Implications and Future Outlook
The situation at SM Entertainment serves as a case study for the K-pop industry at large, which is currently grappling with the "saturation" of the domestic market. For years, the industry thrived on the sale of multiple versions of physical albums to a dedicated fan base. However, as agencies seek to scale, they are forced to look outward.
The transition to an international-first model is capital-intensive and inherently risky. Touring requires significant upfront investment in logistics, marketing, and local infrastructure. If these investments do not yield immediate returns that outpace the decline in domestic album revenue, agencies will inevitably face "transitional" quarters like the one reported by SM.
However, the growth in licensing and non-music revenue segments provides a blueprint for long-term stability. As SM continues to integrate its artists into the global cultural zeitgeist—moving them from being strictly "music acts" to "global brands"—the dependency on the high-volume, low-margin physical music model is expected to diminish.
Investors are now looking toward the upcoming fiscal periods to see if the increased focus on global activities will result in a sustained surge in concert revenue and high-margin licensing deals. While the current 7% stock decline indicates immediate investor anxiety, the underlying growth in the non-musical segments suggests that the structural changes within the company may yield higher profitability in the long run, provided that the global expansion strategy successfully captures the intended market share.
As SM Entertainment navigates this transition, the company’s ability to manage currency exposure and effectively monetize its global IP will be the primary metrics by which the market assesses its future viability. For now, the focus remains on whether the international stage can provide the same reliable revenue growth that the domestic market provided in the industry’s formative years.