Mortgage rates are inching toward the 7% threshold, and while national housing demand appears to be reaching a point of stabilization, the reality for participants on the ground is far more nuanced. For homeowners preparing to list their properties, prospective buyers debating whether to wait for better financing terms, and real estate agents tasked with managing client expectations, the current climate demands a departure from broad, national generalizations. The path back to sub-7% mortgage rates, as highlighted in the latest Housing Market Tracker by HousingWire Lead Analyst Logan Mohtashami, has returned to the table as a viable possibility. However, while weekly pending home sales have shown signs of stabilizing, this trend has not yet translated into a sustained or definitive market recovery.
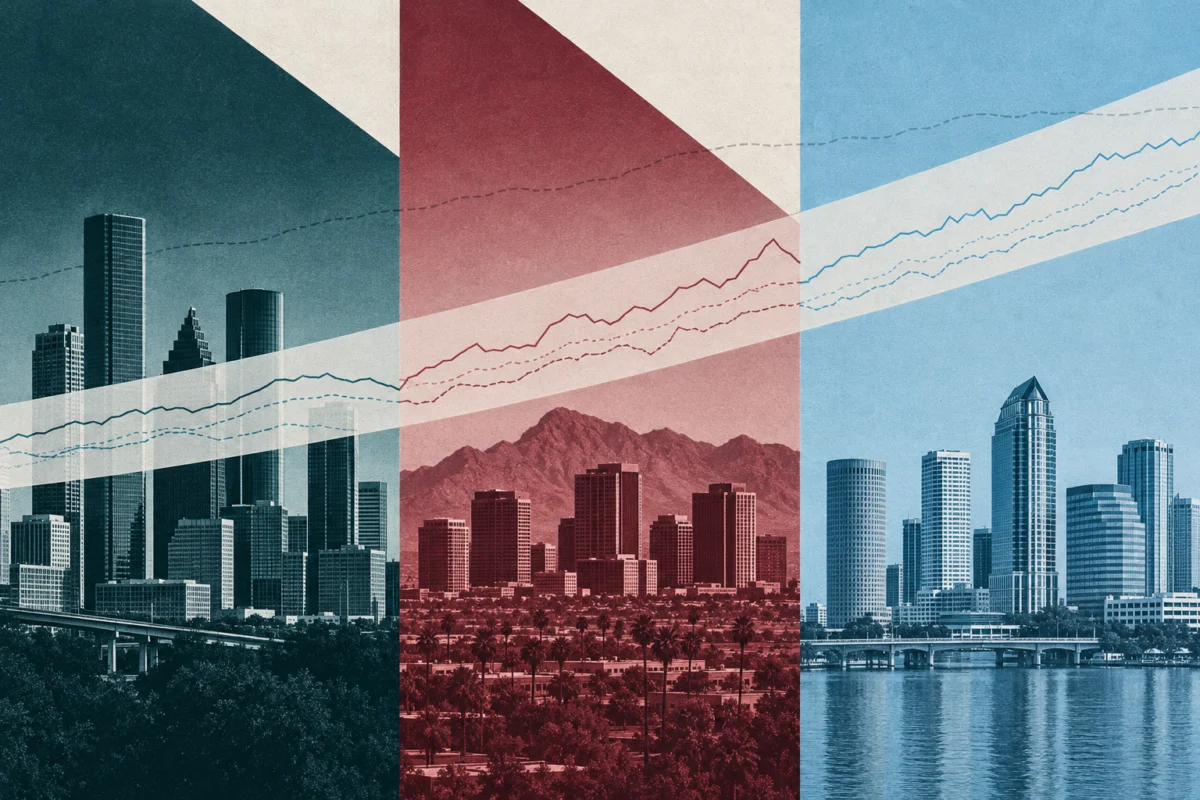
The challenge for real estate professionals lies in the translation of these macroeconomic indicators into actionable insights for clients operating in distinct, local environments. Data synthesized from Houston, Phoenix, and Tampa provides a roadmap for understanding how national signals often fail to capture the granular shifts occurring within city limits. By analyzing the interplay between new listings, pending sales, and active inventory, a clearer picture emerges—one that necessitates a sophisticated, data-driven approach to client advisory.
The Myth of the Uniform Market: A Look at Houston
A frequent point of confusion for sellers is the assumption that “stabilizing demand” is a signal to list immediately. Houston serves as a primary case study for why such assumptions can be misleading without proper local context. During the month of October, the ratio of new pending sales to new listings improved across the Houston metropolitan area. At first glance, this might suggest an uptick in buyer appetite. However, a deeper dive into the data reveals that this improvement was not driven by increased buyer activity. Instead, it was the result of new listings declining at a faster rate than pending sales. In this scenario, the market appeared "stronger" only because the supply of homes contracted more rapidly than the demand for them.
Within the city limits of Houston, the trend inverted. Here, pending sales dropped more precipitously than new listings, forcing the ratio downward. Furthermore, the inventory narrative diverged: active inventory in the Houston metro area was higher than the previous year, yet within the city limits, it was lower. This juxtaposition underscores a fundamental truth for the real estate industry: a regional headline describing a market as "improving" may be entirely irrelevant to the specific street or neighborhood where a client intends to buy or sell.
The implication for agents is clear: national and even regional metrics should serve only as a starting point for dialogue. Professionals must demonstrate to their clients the specific competitive landscape of their immediate area. A seller needs to grasp the reality of their direct competition—how many homes are sitting, how many are moving, and the velocity of price adjustments—rather than relying on the perceived strength of the broader market.
Identifying Converging Signals in Phoenix
The relationship between mortgage rates and market behavior is often oversimplified. Many homeowners believe that a drop in rates will automatically stimulate buyer interest and solidify home values. However, lower financing costs can simultaneously encourage more inventory to enter the market, thereby neutralizing the potential boost to demand. Phoenix offers a cautionary tale regarding what occurs when multiple housing indicators align in a downward trajectory.
Over the most recent four-week window, Phoenix witnessed a clear trend: new pending sales declined at a faster velocity than new listings. Compared to the same period in the previous year, pending activity in Phoenix plummeted by approximately 17%, while the volume of new listings saw a slight increase. When coupled with a steady growth in active inventory—and the fact that more than half of all active listings have undergone a price reduction—the conclusion is evident: seller competition is intensifying.
While these factors do not inherently guarantee a price collapse, they do create significant downward pricing pressure. For the agent, the takeaway is the necessity of holistic analysis. Evaluating pending sales, total inventory, or price-cut shares in isolation is a tactical error. When these indicators move in lockstep, they provide a powerful narrative about the market’s trajectory. Recognizing these patterns allows agents to guide sellers in adjusting their pricing strategies proactively and provides buyers with the empirical evidence needed to negotiate more effectively in an environment where the leverage is shifting.
Recognizing Shifting Conditions: The Tampa Case Study
Market shifts are rarely abrupt; they are often found in the subtle divergence between short-term activity and year-over-year trends. Tampa presents a complex environment that requires a nuanced reading of the data. Within the Tampa city limits, both new listings and pending sales remained largely stagnant over the most recent four-week reporting period. Active inventory stayed below the levels recorded in the previous year, and the percentage of listings experiencing price reductions continued to moderate.
However, a closer look at the short-term trend reveals that inventory has begun to tick upward compared to the preceding four-week cycle. While this does not constitute an immediate market transformation, it represents a data point that warrants careful monitoring. If inventory continues to build while pending activity remains sluggish, sellers in Tampa could find themselves facing heightened competition long before the year-over-year inventory comparisons reflect that reality.
This highlights the importance of toggling between time horizons. Analyzing data through a six-month lens provides a view of recent momentum, while year-over-year data offers the necessary historical context. Both are accurate, yet they tell different stories. The professional’s role is to synthesize these views, ensuring that clients do not base their decisions on potentially outdated annual comparisons when the recent, high-frequency data suggests a change in market direction.
The Professional’s Advantage: Moving Beyond Headlines
In an era where AI-generated market summaries and national headlines are ubiquitous, the value proposition of the real estate professional has shifted. Clients can easily access high-level data; what they cannot easily do is interpret how that data influences their specific financial position. The HousingWire Intelligence framework offers the tools to map these indicators—listings, pending sales, inventory, and price cuts—at a local level, allowing agents to provide the expert analysis that algorithms lack.
The methodology behind these insights is rooted in a rigorous analysis of single-family home performance across all price quartiles. By examining four-week totals for new listings and pending sales, and weekly snapshots for inventory and price-cut shares, professionals can build a defensible case for their advice. For instance, understanding that the "price-cut share" represents a cumulative reflection of the market rather than a snapshot of recent drops is vital for setting realistic expectations during a listing consultation.
Broader Implications and Future Outlook
The housing market is currently in a state of delicate equilibrium. As mortgage rates flirt with the sub-7% range, the potential for increased activity is present, but it is contingent upon how sellers react to existing inventory levels and how buyers perceive their long-term affordability. The current data suggests that we are in a transition phase. Whether this leads to a robust recovery or a period of prolonged stagnation depends on the velocity of these indicators in the coming quarter.
For the industry at large, the lesson of the past few months is one of patience and precision. The "wait-and-see" approach favored by many market participants is understandable, but it is also an opportunity for agents to step in as consultants. By providing a clear, evidence-based assessment of the local market, agents can help clients navigate the noise.
As we move forward, the most successful market participants will be those who resist the temptation to rely on single-metric narratives. Instead, they will embrace the complexity of the current market, utilizing the convergence of supply, demand, and pricing data to inform every decision. Whether it is a seller in Houston looking for clarity amidst conflicting neighborhood data, a buyer in Phoenix analyzing the weight of increased competition, or an investor in Tampa monitoring the subtle rise in local inventory, the goal remains the same: to turn complex, high-frequency data into a clear path forward. In the end, the most effective real estate strategy is not found in national trends, but in the detailed, honest assessment of the home, the competition, and the specific circumstances of the client.