The residential real estate landscape in the United States has undergone a significant shift as the cooling of the pandemic-era housing frenzy gives way to a market defined by buyer leverage. Data covering the three-month period ending August 31, 2026, reveals that nearly 45% of all successful home transactions involved seller-provided concessions. This metric, which tracks non-price incentives such as repair credits, assistance with closing costs, and mortgage-rate buydowns, indicates that sellers are increasingly compelled to sweeten the deal to move inventory in a climate of diminished urgency.
This rise in concessions is not merely a localized trend but a symptom of a broader, sustained transition into a buyer’s market. According to records dating back to 2013, August 2026 stood out as the most advantageous environment for buyers in over a decade. The confluence of increased housing supply and a more cautious pool of prospective homeowners has fundamentally altered the power dynamics of contract negotiations.
A Chronology of Changing Market Dynamics
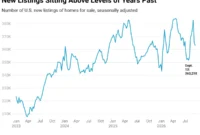
To understand the current state of the housing market, one must examine the progression of the last six years. In 2020, the market was characterized by extreme scarcity, with record-low mortgage rates fueling a competitive frenzy that left buyers with almost zero leverage. By 2021 and 2022, the "lock-in" effect—where homeowners refused to sell to avoid trading in their historically low mortgage rates—kept inventory artificially suppressed, maintaining a heavy seller’s advantage.
However, as the calendar moved into 2025 and 2026, the cumulative effect of higher interest rates and a buildup of new construction inventory began to erode that seller dominance. The current concession rate of 44.7% is a culmination of this cooling period. The trend has been consistent: as the inventory of unsold homes grew throughout the early months of 2026, agents began reporting that buyers were no longer willing to accept homes "as-is" or at premium price points without additional financial support from the seller.
The Geography of Bargaining: Sun Belt Dominance
The prevalence of concessions is not uniform across the United States, with a distinct divide appearing between the Sun Belt region and the coastal tech hubs. In the Sun Belt—a region that saw a massive influx of investment and new residential development during the 2020–2022 migration boom—the market has experienced a sharp correction.
Atlanta, Georgia, currently leads the nation in concession frequency, with sellers providing incentives in 72.8% of transactions. Charlotte, North Carolina, and Phoenix, Arizona, follow closely behind, with concession rates of 67.9% and 67.4%, respectively. This data highlights a specific vulnerability in these markets: the rapid pace of home construction during the pandemic has resulted in an oversupply of inventory relative to current buyer demand.
In Phoenix, for example, the year-over-year increase in concessions is a staggering 15.3 percentage points. This reflects a local market where sellers are competing not only against other existing homeowners but also against major developers offering aggressive incentives, such as interest rate buydowns that can save buyers hundreds of dollars in monthly payments.
The Contrast: Resilience in Tech-Centric Markets
Conversely, the markets where concessions are least common—San Jose, New York, and San Francisco—reveal the persistent strength of areas tied to the artificial intelligence boom and high-income employment sectors. In San Jose, only 4.2% of home sellers provided concessions in August, the lowest in the nation.
These regions function as a stark counter-narrative to the Sun Belt. In San Francisco, where demand remains high due to the influx of capital and talent into the AI sector, the market remains a firm seller’s domain. Because the number of affluent buyers in these specific regions still outpaces the supply of available housing, sellers face little pressure to offer closing cost assistance or repair credits. The leverage remains firmly in the hands of the property owner, who can generally command full asking price without providing additional financial sweeteners.
Agent Perspectives on Buyer Sentiment
The current climate has fundamentally changed the psychology of the homebuyer. Amanda Peterson, a Redfin Premier agent based in Dallas, notes that today’s buyers are acting with a level of scrutiny that was absent just a few years ago. "Buyers know they can be picky," Peterson observed. "They’re asking for every concession under the sun."
Peterson’s observations provide anecdotal weight to the statistical reality. In competitive, inventory-rich markets, buyers are treating real estate transactions with a consumer-goods mentality. The willingness of buyers to walk away from deals—even those that are nearly finalized—due to minor aesthetic preferences or secondary features, such as kitchen size or laundry room layout, suggests that the fear of missing out (FOMO) has been replaced by a "wait and see" approach.
Furthermore, the influence of new home builders cannot be overstated. By offering $10,000 to $20,000 in concessions as a baseline, builders have set a benchmark that sellers of existing homes are now forced to match if they wish to remain competitive. This creates a ripple effect throughout the local housing market, forcing traditional sellers to absorb costs they might have ignored in a tighter, less competitive cycle.
Data Analysis: The Intersection of Price Drops and Concessions
While concessions are a primary tool for closing deals, they are often paired with traditional price reductions. The data shows that 15.8% of homes sold in August featured both a price drop and a concession. This figure is the highest recorded for August since data collection began, signaling that for a segment of the market, neither price cuts nor concessions alone are sufficient to attract a buyer.
This dual-strategy approach is most common in markets where time-on-market metrics are lengthening. When a property lingers, sellers often move from a "price-cut" strategy to a "concession-plus" strategy, hoping that by offering to cover closing costs or perform repairs, they can bridge the gap for a buyer who may be struggling with high monthly mortgage obligations.
Broader Implications and Economic Outlook
The rise in concessions carries significant implications for the broader U.S. economy. First, it acts as a "hidden" form of price correction. While official home price indices may show that home values are holding steady, the effective price—the amount the buyer actually pays after accounting for concessions—is often lower. This nuance is critical for economists and policymakers who track housing affordability.
Second, the trend highlights the growing importance of the "total cost of ownership" for the average American household. With mortgage rates remaining elevated compared to the historic lows of the early 2020s, the ability of a buyer to secure a concession—particularly a mortgage-rate buydown—can be the deciding factor in whether a home is truly affordable.
Finally, the geographical disparity suggests that the "national" housing market is increasingly a collection of fragmented local markets. While national averages provide a macro view, the reality on the ground in the Sun Belt is vastly different from that in the Bay Area. Investors and prospective homeowners should monitor these trends closely, as the shift toward buyer leverage in the Sun Belt may continue to widen if inventory levels remain high or if further regional economic shifts occur.
As we move into the final quarter of 2026, the reliance on concessions will likely remain a hallmark of the housing market. For sellers, the mandate is clear: in an era of abundant supply and discerning buyers, flexibility is the only path to a successful closing. For buyers, the current environment offers a rare opportunity to exert influence and secure financial support that, until recently, was almost entirely absent from the negotiation table.