Palantir Technologies delivered a landmark third-quarter 2026 earnings report this week, showcasing a historic revenue milestone that underscores the company’s aggressive pivot toward the commercial artificial intelligence sector. Reporting $2.31 billion in total revenue—a 96% increase year-over-year—the company officially shattered the $2 billion quarterly threshold for the first time in its history. Despite this massive financial performance, which handily outpaced analyst consensus expectations of $2.18 billion, Palantir’s stock experienced a lukewarm reception from investors, reflecting broader market anxieties regarding the sustainability of enterprise sales cycles in the current AI gold rush.
A Financial Milestone: The Numbers Behind the Growth
The fiscal results released Monday paint a picture of a company in a state of rapid transformation. Beyond the top-line revenue surge, Palantir reported adjusted earnings per share of $0.44, comfortably beating the market forecast of $0.41. This performance represents a 20% growth compared to the previous quarter, a testament to the accelerating adoption of its Artificial Intelligence Platform (AIP).
Perhaps the most significant takeaway from the Q3 results is the tectonic shift in Palantir’s revenue composition. For the first time, U.S. commercial revenue has eclipsed the company’s historically dominant U.S. government business. The commercial division brought in $984 million—a staggering 148% increase from the same period last year—compared to $953 million from the public sector. This inversion suggests that Palantir’s strategy of “forward-deployed” engineering, which allows firms to train custom models securely on proprietary data without exposing sensitive intellectual property to third-party labs, is gaining massive traction among Fortune 500 enterprises.
Chronology of the 2026 Pivot
To understand the weight of these results, one must examine the timeline of Palantir’s evolution over the last eighteen months. Throughout early 2025, the company focused heavily on bridging the gap between its legacy government-contract model and the high-speed, high-stakes world of commercial AI.
By the first quarter of 2026, Palantir had begun signaling that its AIP software was becoming the standard for enterprises looking to deploy large language models (LLMs) without compromising data sovereignty. The second quarter of 2026 served as a record-setting period for Total Contract Value (TCV), where the company secured $2.13 billion in new enterprise commitments.
However, the third quarter of 2026, while financially superior in realized revenue, showed a deceleration in new contract value, which dipped to $1.46 billion. This fluctuation has become the focal point of the current investor debate: while existing customers are spending more and deploying faster, the pipeline of massive, long-term legacy contracts is showing signs of becoming more fragmented.
The Paradox of Enterprise AI Adoption
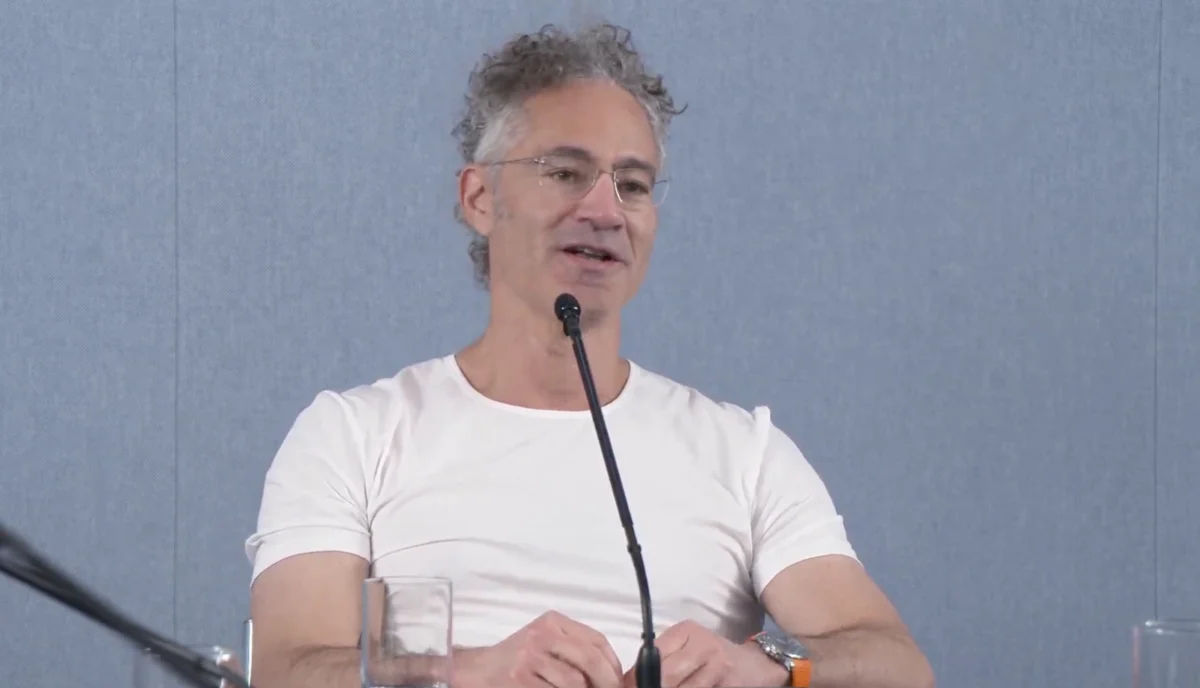
During the quarterly earnings call, CEO Alex Karp addressed the changing nature of corporate procurement. He noted that the typical enterprise bureaucracy—which once required 18 to 24 months of vetting for major software acquisitions—is being bypassed in favor of shorter, agile trials. While this allows Palantir to gain entry into accounts much faster than in previous years, it creates a new operational reality: contracts are shorter in duration, though they possess a high potential for dramatic expansion.
This “trial-first” mentality is a hallmark of the current enterprise AI landscape. Corporations are eager to see tangible ROI before committing to multi-year, multi-million dollar lock-ins. For Palantir, this creates a double-edged sword. On one hand, the barrier to entry for new clients has lowered; on the other, the risk of churn increases if the software does not deliver immediate, demonstrable utility.
Karp, characteristic of his unconventional communication style, dismissed concerns about this trend during the call. He likened the company’s current standing to that of a popular figure in a high school hierarchy, emphasizing that once a client integrates Palantir’s infrastructure, the "stickiness" of the platform makes it nearly impossible to replace. "Once you go Palantir, you don’t go back," Karp stated, framing the current surge in demand as a fundamental shift in how corporations manage their data architecture.
Analysis: Market Implications and Future Outlook
The market’s hesitant reaction to the earnings beat can be attributed to the deceleration in enterprise TCV compared to the second quarter. Investors are attempting to discern whether the lower TCV represents a seasonal cooling-off period or a structural shift toward smaller, more incremental spending by corporations.
However, the company’s guidance remains bullish. Palantir has raised its full-year 2026 revenue guidance to a 91% year-over-year growth rate, with U.S. commercial revenue projected to exceed $3.559 billion—a 143% increase. These figures suggest that management is confident that the "shorter duration" contracts will eventually aggregate into larger, more stable revenue streams as these pilot programs scale.
The fourth quarter will be critical for validating this thesis. Historically, the final quarter of the fiscal year is when enterprises clear their remaining capital expenditure budgets, often leading to the signing of the largest tech contracts of the year. If Palantir can convert its current influx of short-term trial users into enterprise-wide, multi-year licenses, it will likely solidify its position as the primary operating system for the modern AI-driven corporation.
The Competitive Landscape
Palantir’s success is not occurring in a vacuum. It is competing against a wave of cloud providers, boutique AI consultancies, and internal IT departments attempting to build proprietary solutions. What distinguishes Palantir, according to market analysts, is its focus on the "plumbing" of AI—the security, data integration, and governance layers that allow a company to use AI safely.
While competitors often focus on the consumer-facing or creative aspects of AI, Palantir has doubled down on the enterprise-critical need for data privacy. By ensuring that client data never leaves the secure, private environments managed by the software, Palantir has addressed the primary concern of C-suite executives who are otherwise terrified of data leaks or hallucinations.
Economic and Regulatory Considerations
Beyond the financial metrics, Palantir’s growth trajectory faces potential headwinds in the form of global regulatory scrutiny. As the company becomes the backbone of critical infrastructure for an increasing number of Fortune 500 firms, it will inevitably face questions regarding data ethics, algorithmic transparency, and its role in potential labor displacement.
Furthermore, the macroeconomic environment remains a variable. Should the global economy face a downturn in 2027, the first budgets to be scrutinized are typically discretionary software trials. Palantir’s ability to prove that its software is an "essential utility" rather than a "nice-to-have" tool will be the ultimate test of its business model.
Conclusion: A Pivotal Moment
The Q3 2026 report serves as a bridge between Palantir’s past as a specialized, government-facing contractor and its future as a ubiquitous commercial AI provider. While the deceleration in TCV has introduced a measure of caution into the stock’s performance, the sheer velocity of its U.S. commercial growth suggests that the demand for robust, secure AI is at an all-time high.
As the company enters the final quarter of the year, all eyes will be on the conversion rate of those early-stage, short-term commercial contracts. If Karp’s prediction holds true—that once an enterprise adopts Palantir, they are locked in for the long term—then the short-term volatility in contract value may simply be a byproduct of a rapidly expanding, rather than contracting, customer base. The coming months will determine whether Palantir can sustain this momentum and transform its "football team captain" status into enduring, long-term market dominance.