PennyMac Financial Services Inc. (PFSI) reported its financial results for the third quarter of 2026 on Thursday, revealing a complex fiscal narrative defined by a struggling originations sector and a robust, expanding mortgage servicing business. The California-based mortgage giant posted a net income of $29 million for the period spanning June through September. While this figure represents an 84% decline compared to the same period in 2025, it marks a significant 32% sequential improvement over the second quarter of 2026. As the company navigates a volatile macroeconomic environment, it is actively implementing aggressive cost-cutting measures, including workforce reductions, and preparing for a series of high-level executive changes slated for the start of 2027.
A Period of Market Volatility and Operational Realignment
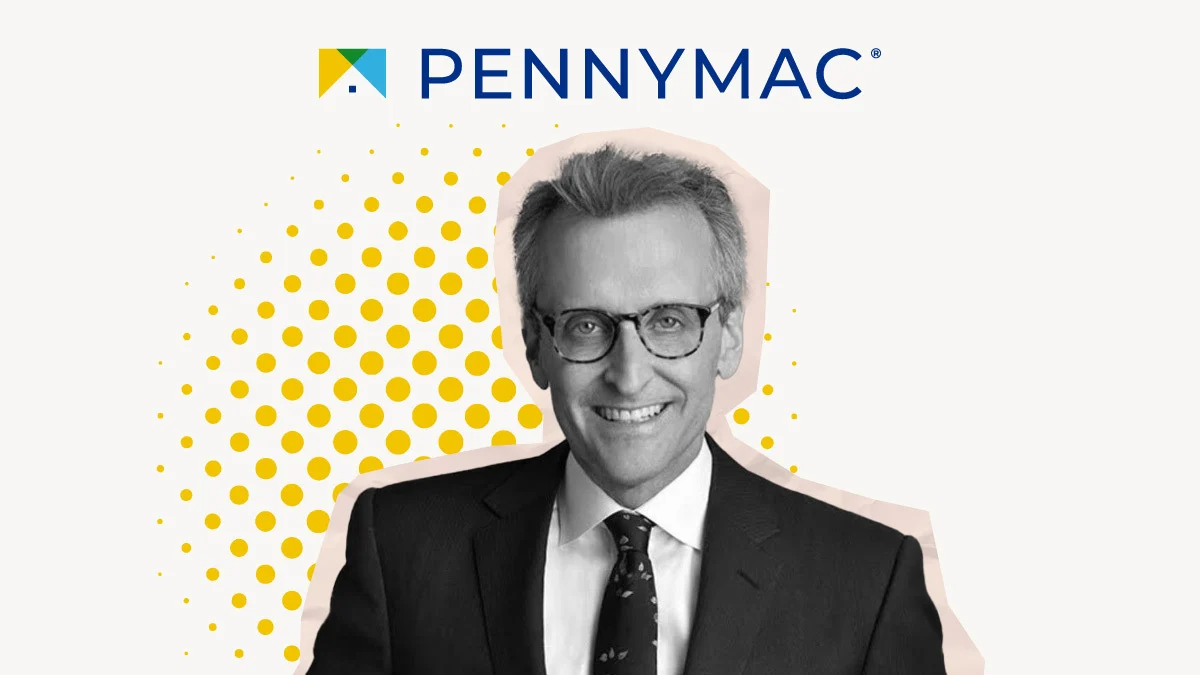
The third quarter of 2026 was characterized by a rapid and unexpected surge in interest rates. David Spector, chairman and CEO of PennyMac, noted during the company’s earnings call that the 30-year fixed mortgage rate rose by approximately 90 basis points during the quarter, reaching an average of 7.4% by the end of September. This shift created one of the most restrictive environments for mortgage originations since 2023.
In response to these headwinds, PennyMac has initiated a comprehensive cost-reduction strategy aimed at achieving $160 million in annualized expense savings between the second quarter of 2026 and the first quarter of 2027. A central component of this strategy is the reduction of its workforce. While the exact number of affected employees was not disclosed, a company spokesperson confirmed that the cuts were targeted at mortgage fulfillment operations, citing the need to align internal capacity with diminished loan volumes.
The Changing of the Guard: Executive Leadership Transitions
Beyond financial maneuvering, PennyMac announced a significant reorganization of its C-suite effective January 1, 2027. Kevin Ryan, currently serving as the company’s chief strategy officer, has been tapped to succeed Dan Perotti as chief financial officer. Perotti, a cornerstone of the company’s financial leadership since 2008 and CFO since 2021, will maintain his current role through the remainder of the year and transition into an advisory capacity through the first quarter of 2027 to ensure a seamless handover.
Additionally, the company announced the upcoming retirement of Doug Jones, the president and chief mortgage banking officer. Jones, who has been instrumental in the company’s operational growth since 2011, will depart on June 30, 2027. CEO David Spector expressed strong confidence in the depth of the company’s leadership bench, emphasizing that these transitions are part of a long-term strategy to drive shareholder value despite current market pressures.
Production Segment Under Pressure
The impact of the high-rate environment was most visible in the company’s production segment, which swung to a pretax loss of $7 million in the third quarter. This stands in stark contrast to the $38 million in pretax income generated in the second quarter and the $123 million reported in the third quarter of 2025.
Total loan acquisitions and originations for the quarter reached $24.4 billion in unpaid principal balance (UPB), representing a 30% decline from the $34.9 billion recorded in the second quarter and a 33% drop from the $36.5 billion in the same period last year. The decline was widespread across all primary channels:
- Consumer Direct: Fallout-adjusted locks fell to $2.8 billion, down from $4.5 billion in the prior quarter, largely due to a contraction in refinance demand.
- Broker Channel: Fallout-adjusted locks dropped to $4.7 billion from $6.5 billion in the second quarter.
- Correspondent Channel: Locks decreased to $15.6 billion from $20.5 billion in the prior quarter.
Production revenue margins also saw a slight compression, falling to 76 basis points, down from 77 basis points in the second quarter. Spector highlighted that the company is responding to these challenges by accelerating the automation of labor-intensive fulfillment workflows, a move intended to decouple platform capacity from staffing requirements and allow for leaner operations in future periods of volatility.
Servicing Portfolio Growth and Strategic Deleveraging
While the production side faced significant headwinds, the company’s mortgage servicing rights (MSR) business provided a critical counterbalance. As of September 30, 2026, PennyMac’s servicing portfolio stood at $737 billion in UPB. This portfolio is expected to grow significantly, potentially exceeding $1 trillion, following the anticipated closure of the company’s acquisition of Cenlar Capital Corp.
Originally announced in February with an initial year-end 2026 target, the $257.5 million acquisition of the nation’s second-largest subservicer has been extended into the first quarter of 2027. This acquisition marks a historic milestone for PennyMac as its first major M&A activity, underscoring the company’s commitment to scaling its servicing operations.
In the third quarter, the servicing segment generated $99 million in pretax income, a substantial increase from $22 million in the previous quarter. When excluding fair value changes and hedge results, the segment’s profitability was even more pronounced, reaching $132 million. The improvement was largely driven by a decrease in prepayment speeds, which dropped to 8.1% from 11.6% in the second quarter, thereby reducing amortization costs.
Capital Management and Future Outlook
To bolster its balance sheet, PennyMac has reached an agreement to sell $29 billion in UPB of low-coupon MSRs. The transaction is expected to close in the fourth quarter and generate approximately $490 million in net proceeds. Management intends to deploy this capital primarily to pay down debt and repurchase common shares, noting that the stock is currently trading at a significant discount to book value.
This divestiture is part of a broader deleveraging effort. CFO Dan Perotti noted that the company’s nonfunding leverage, which rose to 1.9x following the recent rate spike, is projected to return toward the target of 1.5x as the debt paydown takes effect and market conditions stabilize.
Industry Implications and Broader Context
The financial results from PennyMac serve as a bellwether for the broader mortgage industry, illustrating the "natural hedge" business model that firms are increasingly forced to adopt. By balancing originations with servicing, PennyMac is attempting to insulate itself from the cyclical nature of mortgage rates. However, the severity of the 2026 rate environment has tested the limits of this model, leading to the difficult decisions regarding workforce reductions and asset sales.
Analysts suggest that PennyMac’s focus on automation and capital discipline will be critical in the coming quarters. The company’s ability to successfully integrate the Cenlar acquisition will likely determine its competitive standing in the servicing market throughout 2027. As the company transitions its leadership team, the market will be watching closely to see if the new executive lineup can effectively navigate the recovery phase of the current interest rate cycle.
Ultimately, the results reflect an industry in transition. With mortgage rates remaining at multi-year highs, the focus for lenders like PennyMac has shifted from pure volume growth to efficiency, operational optimization, and the long-term sustainability of their servicing portfolios. While the immediate outlook remains constrained by macro-economic volatility, management’s commitment to a leaner operational structure and strategic capital reallocation signals a focused attempt to remain resilient in a challenging financial landscape.